Same project, same costs. Change how it gets paid,
and the lender's verdict moves from Difficult to Bankable.
A project finance model for Japan's offshore wind pipeline. Calculate LCOE, IRR, and debt service coverage (DSCR) under your own financing, cost, and revenue assumptions.
Tap FIP or LTDA to switch. LTDA pays a fixed annual amount per kW of capacity instead of a price per kWh. Illustrative only. Not financial, investment, or bidding advice.
Projects get built when someone lends against them
An offshore wind project does not get built because it is technically possible. It gets built because someone lends against it. When a Japanese project stalls, the reason is more often the financing terms than the engineering.
Lenders and sponsors are asking different questions. The four numbers the simulator calculates each measure a different point in the project's cash flow.
How many times over the cash covers the payment. Below a certain level the terms get reworked, or the loan does not happen.
The simulator moves all four at once. Take 10% off CAPEX and see how far DSCR recovers. Switch the revenue model to LTDA and see whether the verdict changes. Change one assumption and watch the rest respond.
All outputs are computed in real terms (constant 2026 JPY). WACC and loan rate inputs are therefore read as real rates. METI FIP and FIT auction prices are nominal fixed-price contracts, so their real value erodes over the contract term.
Three verdicts, and only the top one asks about equity
Minimum DSCR results are classified against standard project finance lender thresholds. The top band also requires an equity return that clears a typical sponsor hurdle, so coverage alone is not enough to reach it.
The same switch, in the simulator
The 525 MW case from the top of the page, switched from FIP to the Long-term Decarbonization Power Source Auction (LTDA).
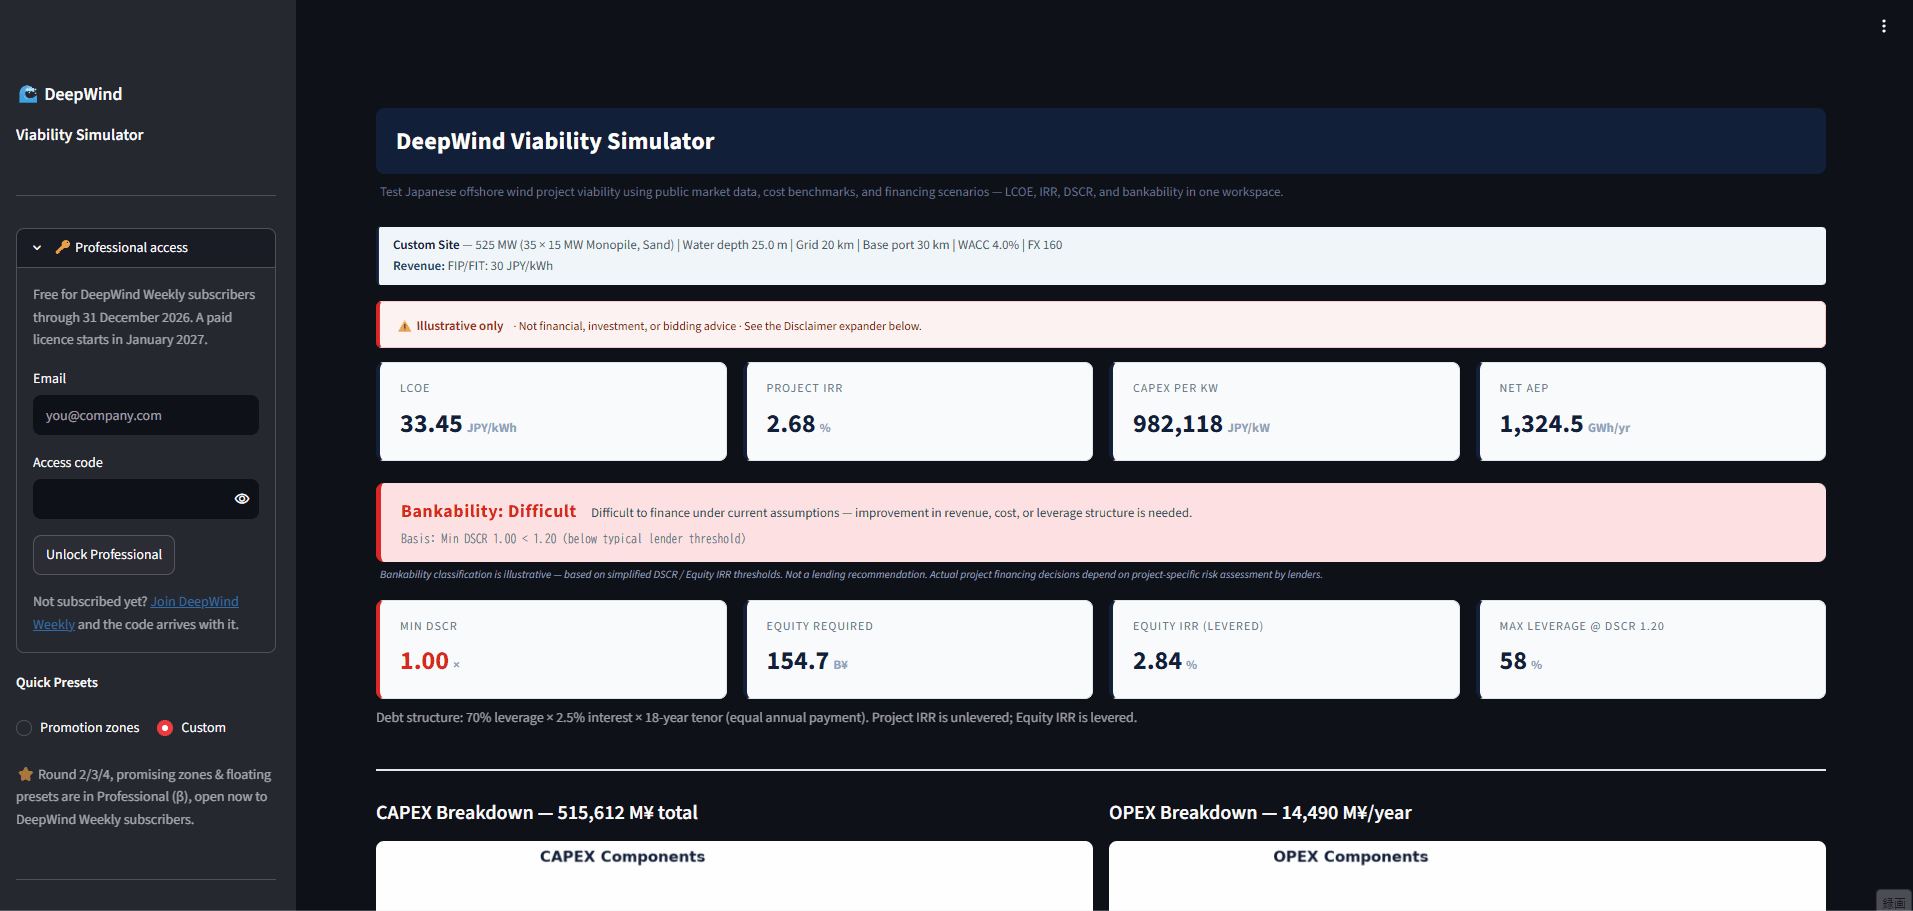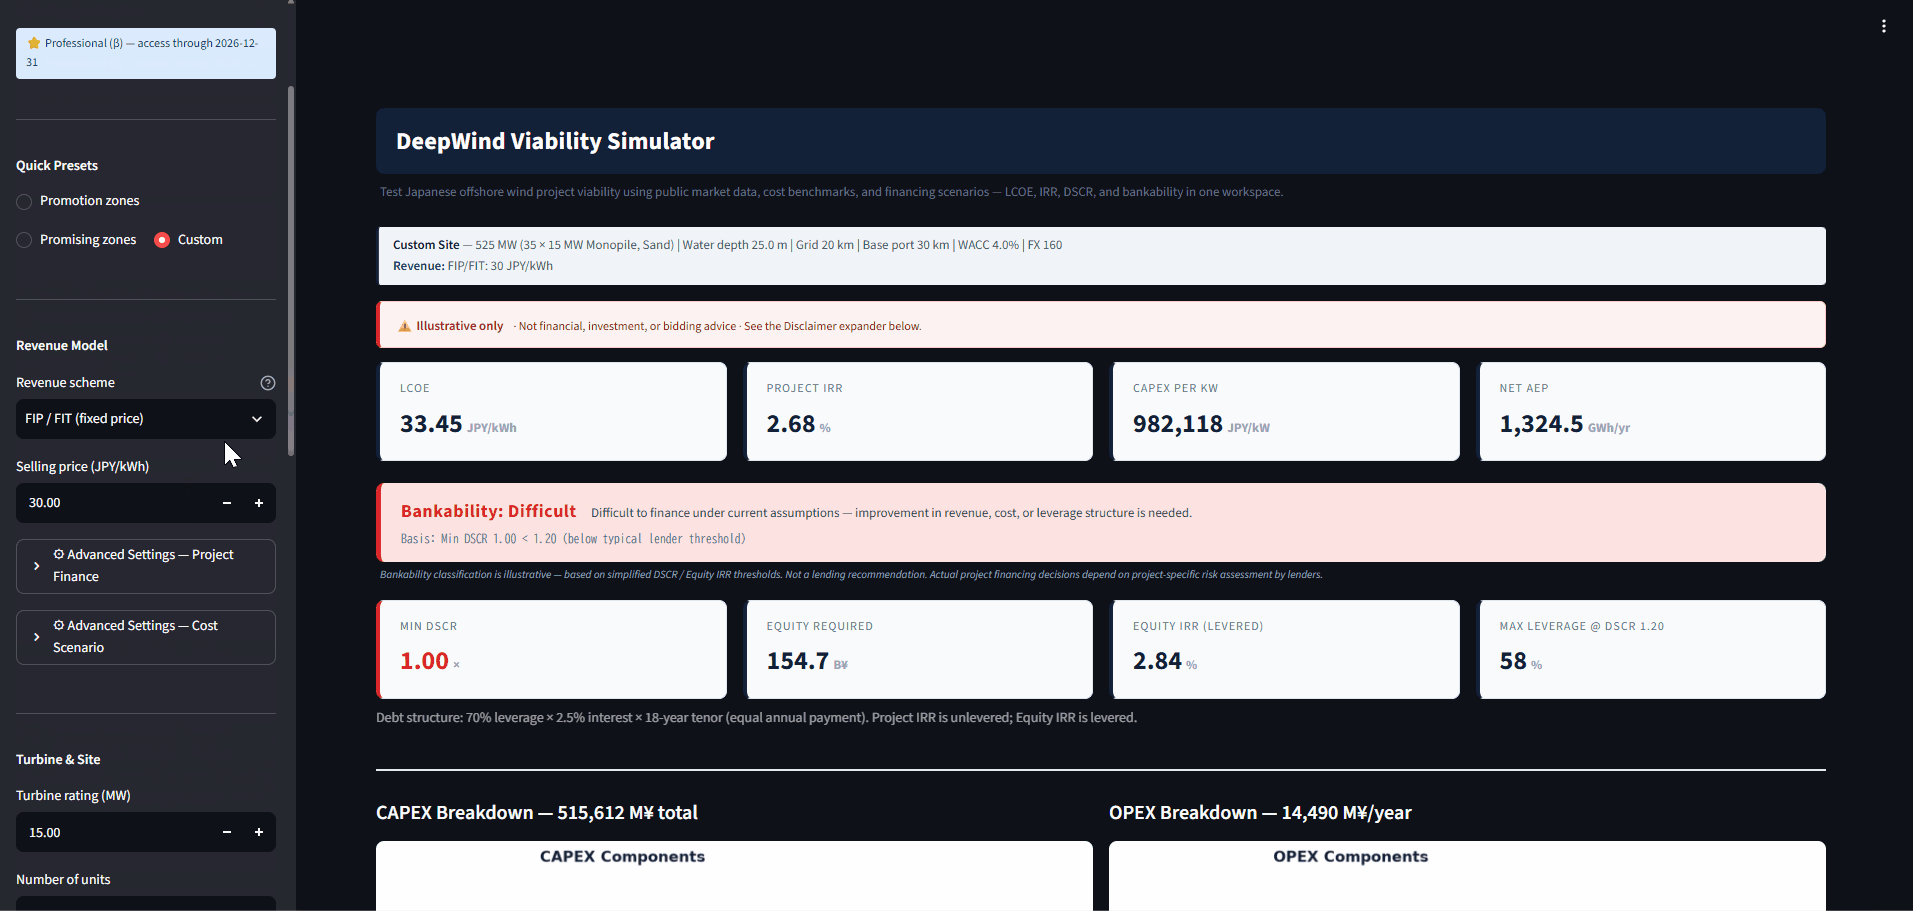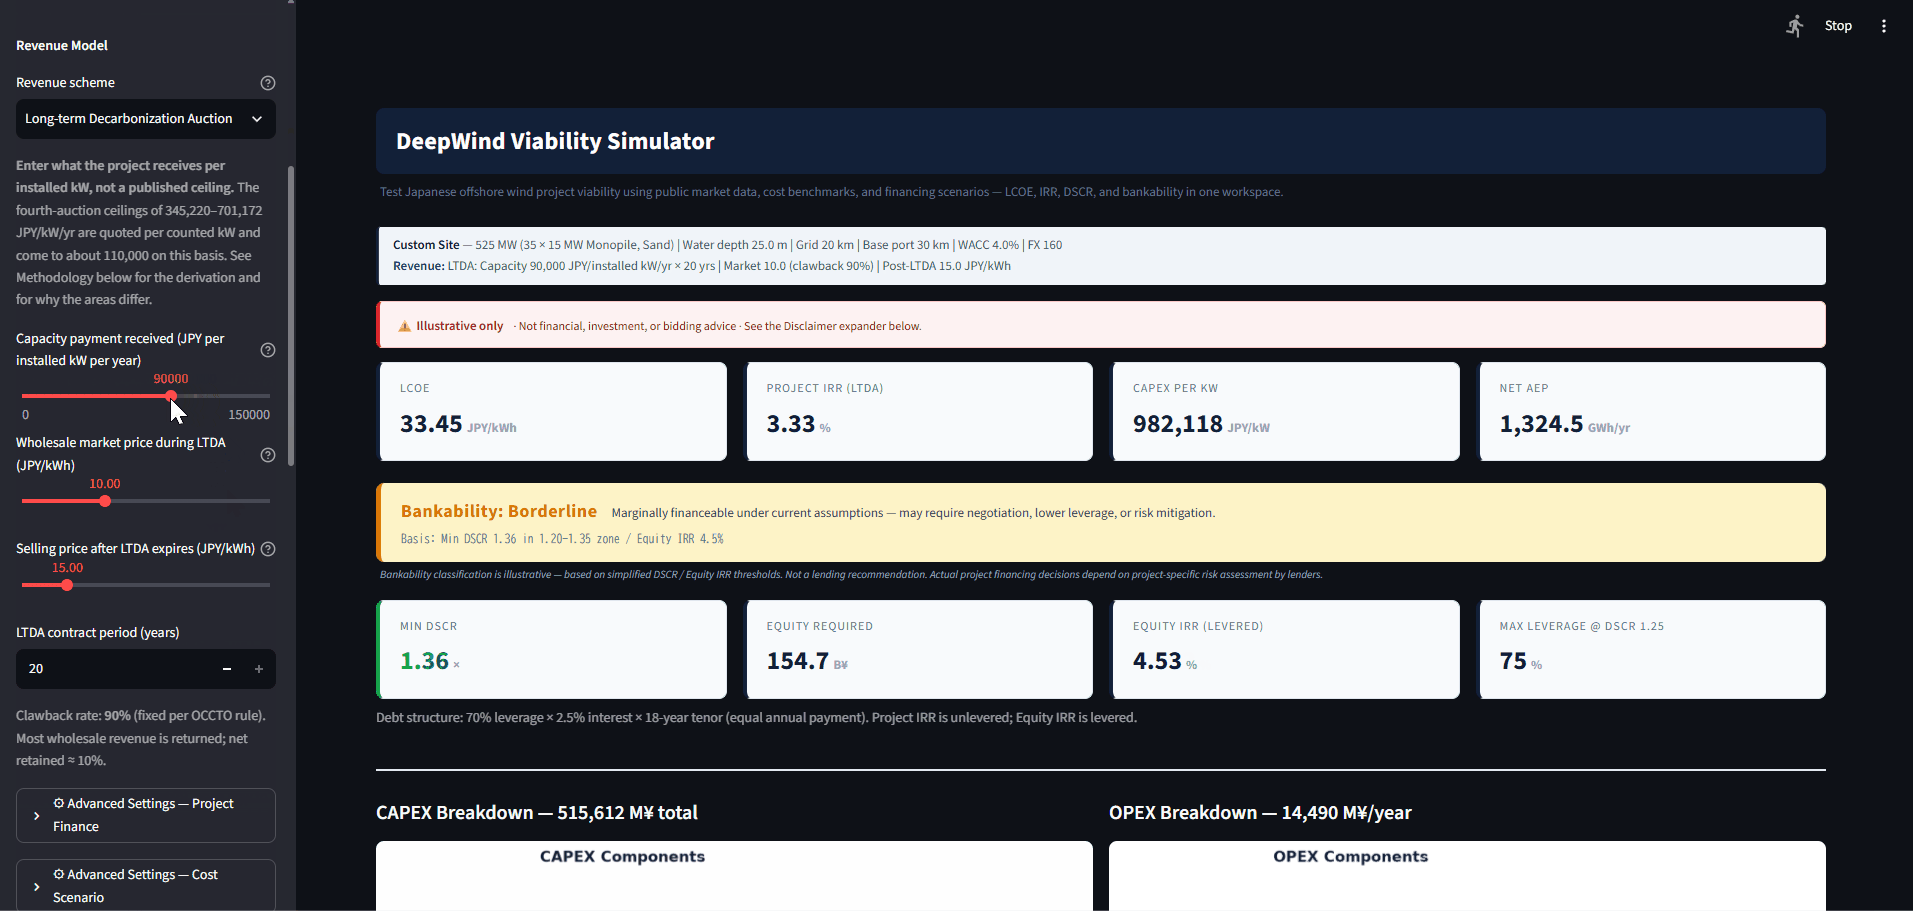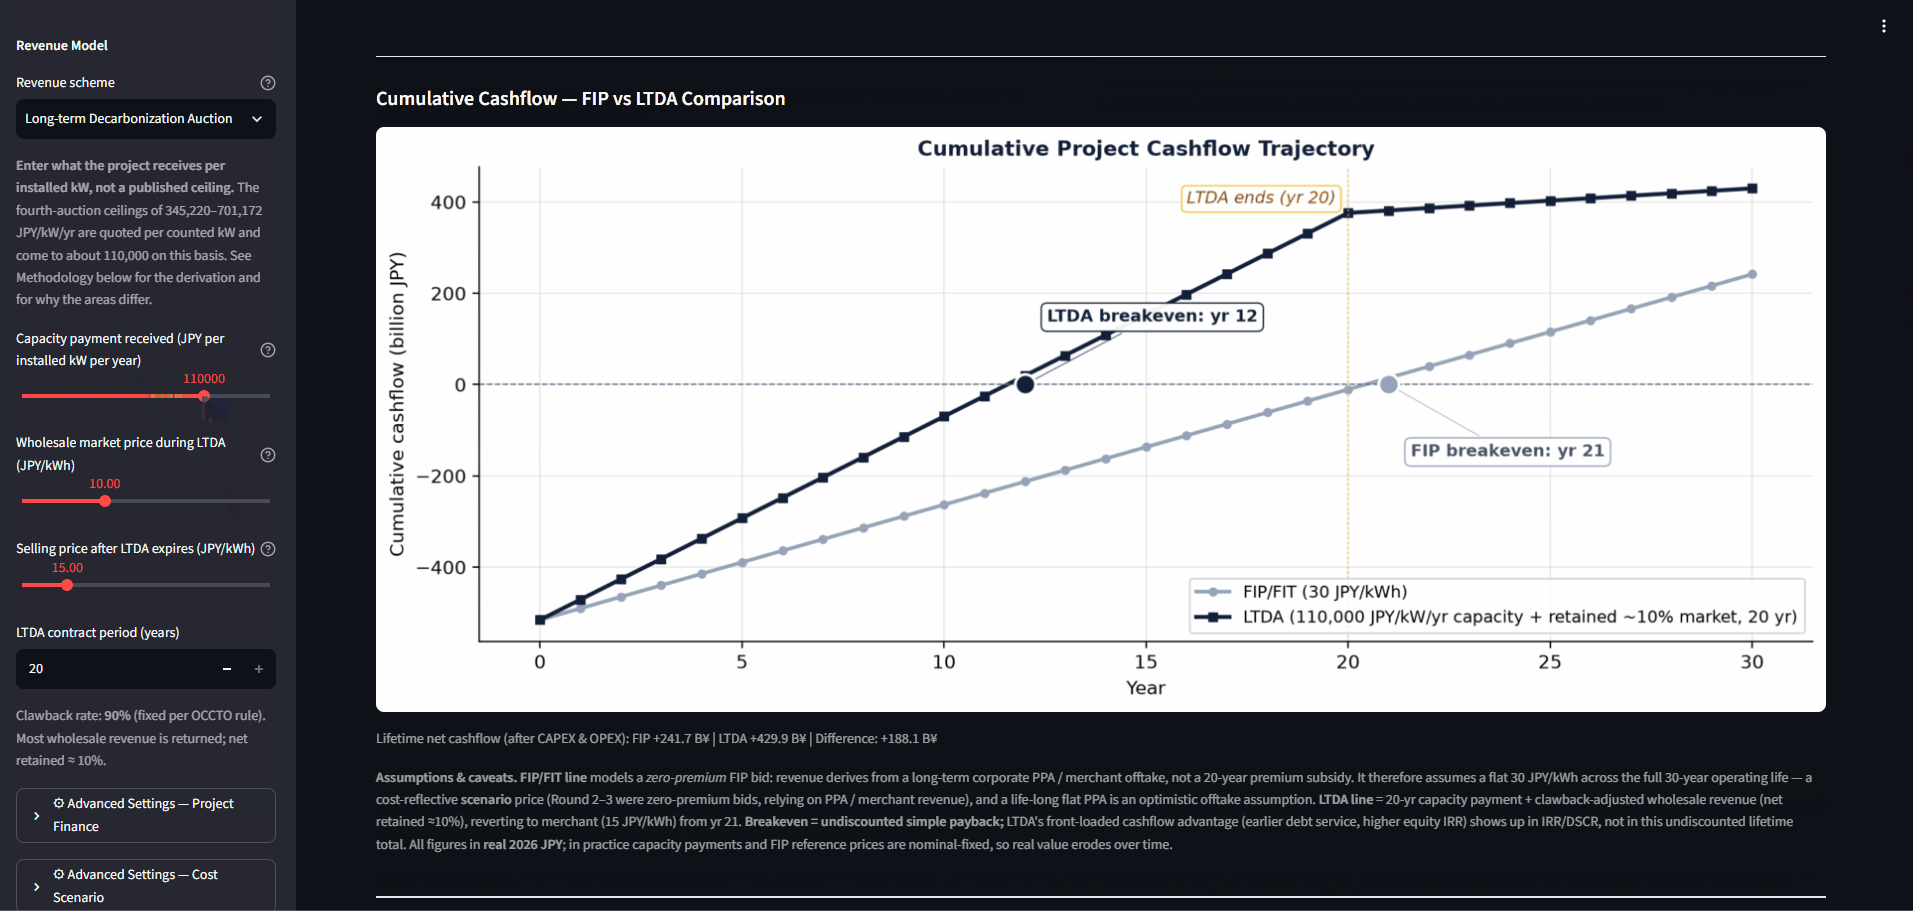
Under FIP at 30 JPY/kWh the case returns a minimum DSCR of 1.00, inside the Difficult band. Under LTDA with a capacity payment of 110,000 JPY per installed kW per year it returns 1.77, inside the Bankable band, and cumulative cashflow crosses zero in year 12 rather than year 21. That 110,000 is what the project receives per installed kW. The published fourth-auction ceilings of 345,220 to 701,172 JPY/kW/yr are quoted per counted kW, after dividing by the area adjustment coefficient, and come to about the same figure on a per-installed-kW basis. Illustrative only. Not financial, investment, or bidding advice.
Two access levels
Free
Explorer
- Round 1 re-tender project presets
- FIP / FIT revenue scenarios
- WACC sensitivity
- No registration required
Subscriber beta
Professional β
- 21 zones in total: the promotion zones, covering the Round 1 re-tender through Round 4 sites, plus the promising zones
- LTDA scenarios
- 8-variable tornado sensitivity
- Fixed-bottom and floating foundations
- Full parameter control
How to unlock. Professional (β) is open to DeepWind Weekly subscribers. The access code goes out by email. Once you have it, open Professional access in the simulator sidebar and enter your email and the code. No approval step and no waiting.
Beta terms. Free to subscribers until 31 December 2026, then a paid licence from January 2027. Saying that here so nothing about it comes as a surprise later.
Not subscribed yet? Join DeepWind Weekly and the code arrives with it. The Weekly is free and stays free.
Reports say whether a project is bankable. The Simulator shows under what conditions
DeepWind's premium reports fix the assumptions, document the method, and give a verdict at a point in time. The Simulator is the calculation layer alongside them. It runs the same framework under your own financing costs, FX rates, or revenue scenarios.
👉 Explore DeepWind Premium Reports
Terms used on this page (19)
Finance
Levelized cost of energy: the average cost of each kWh the asset produces over its life.
The return on the project itself, with the effect of borrowing removed, so projects can be compared on the same basis.
The return earned by the people who put up the equity. It moves with the borrowing terms.
Debt service coverage ratio: how many times over the cash available covers the debt payment due.
Weighted average cost of capital: the average return the project pays on the money it raises.
The total cost of building the project and bringing it into operation.
Whether a lender can conclude that the project is financeable.
Funding raised against the revenue the project itself generates, rather than against the sponsor's balance sheet.
The share of total cost funded by debt, and the number of years over which that debt is repaid.
Real figures are held at one year's prices with inflation removed. Nominal figures are at the prices of the day, so their real value erodes as prices rise.
Policy
A scheme that buys the electricity produced at a fixed price.
A scheme that pays a premium on top of the market price.
The Long-term Decarbonization Power Source Auction, which grants long-term fixed revenue against capacity.
Revenue paid per kW of installed capacity per year, rather than per kWh generated.
A sea area the government has designated for a public tender.
A sea area identified as a candidate that may progress to a tender once conditions are met.
Technology and analysis
A foundation fixed directly to the seabed, used down to roughly 50 m of water depth.
A turbine carried on a floating platform held by moorings, used where fixed-bottom foundations cannot reach.
The share of the output the turbine would have produced had it run at rated power continuously.
A ranking of assumptions by how far each one moves the result, largest effect first.
Ready to run the numbers?
Launch Simulator →
Defaults: 70% debt / 2.5% rate / 18-year tenor. LCOE in real terms (constant 2026 JPY). Full methodology in-app.
Leave feedback on the Simulator